The Thesis
The topline decline continues for Griffon Corporation (NYSE: NYSE:GFF) moving into the second half of FY24, however at a moderate rate. I expect this to continue further in the near term due to the ongoing weaker demand in the company’s CPP segment primarily in the U.S. and the UK, however, door volume growth followed by increased residential orders should largely offset this impact. Long-term demand prospects remain favorable due to demographic housing trends that should drive demand for the company’s product in the coming years. Margins also look good as the company continues to benefit from its Global outsourcing initiative, a key element of margin improvement in the longer term. The company’s stock valuation looks attractively priced versus its sector median, which along with a good long term outlook makes this stock a decent buy at the current level.
GFF’s Business Overview
Griffon Corporation is a diversified company that provides products and services related to home building, consumers, and professionals primarily across the United States, Canada, Europe, and Australia through its subsidiaries. The company mainly operates under two segments:
-
Home and Building Products (HPB): The segment includes manufacturing and marketing of residential as well as commercial garage doors and rolling steel through its subsidiary, Clopay Corporation for new commercial construction, repair, and home remodeling applications.
-
Consumer and Professional Products (CPP): This segment produces and sells landscaping and garden tools including spades, hoes, cultivators, weeders, post-hole diggers, scrappers, edgers, etc. This segment also includes pruning products and striking tools.
Leading Brands in GFF’s core categories (Company presentation)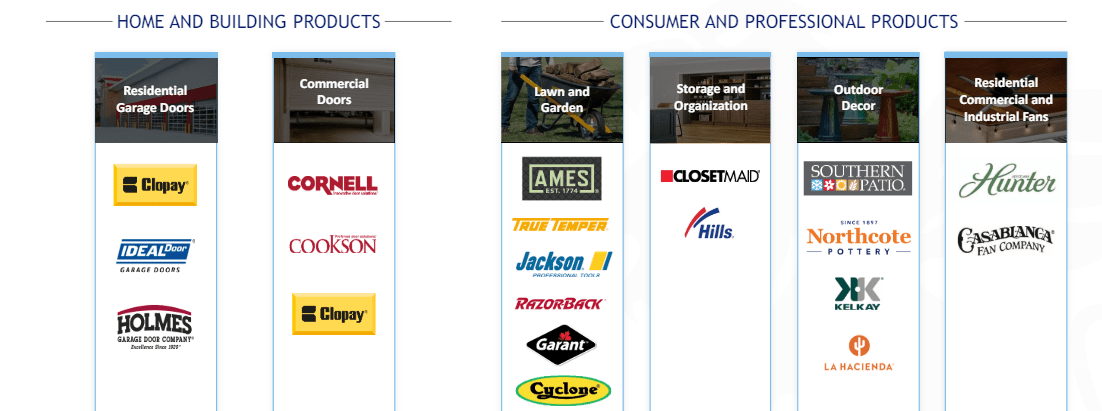
Last Quarter Performance
The company’s topline continued to decline maintaining its streak for the straight fifth quarter as it entered the second half of 2024. The company reported its second-quarter revenue of $673 million, down approximately 5.4% versus the prior-year quarter. The decrease was primarily driven by volume loss in the Consumer and Professional Products segment due to reduced demand across North America and the UK resulting in a double-digit revenue decline for the segment. The Home Building Product on the other hand was down 1% as the negative impact of unfavorable product mix more than offset benefits from volume growth in the segment during the second quarter of FY24.
GFF segment wise sales (Research WIse)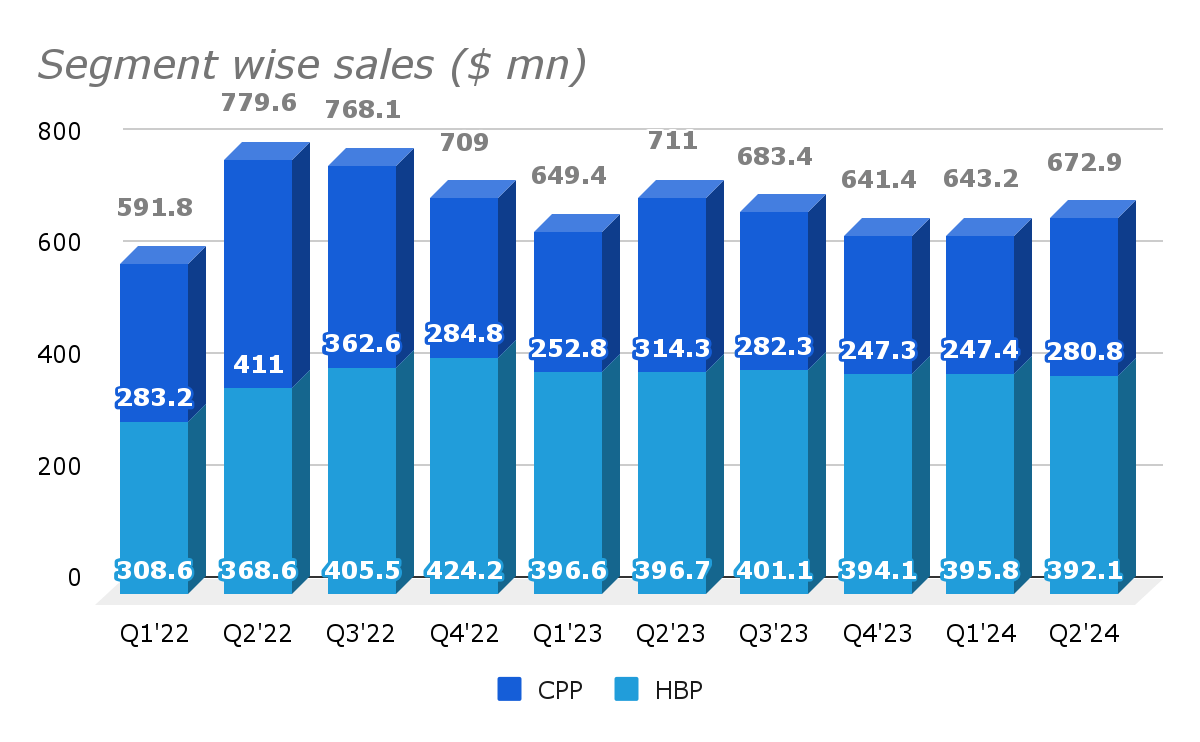
While the topline was down in mid-single digits, the company’s margins came in better than expected due to strong margin performance in the CPP segment, which delivered a 2% growth in EBITDA despite a 10.7% contraction in its sales. The CPP segment’s margin grew 100 bps to 7.2% year on year due to improved production cost in North America, while the HPB segment adjusted EBITDA margin came in at 32.9%, a slight decline of 30bps versus the same quarter a year ago, primarily driven by increased labor and distribution costs. The company’s bottom line performance was also strong during the quarter as the company continued its streak of beating estimates. During the last quarter, the company reported its EPS at $1.35, beating the consensus estimates by $0.51.
Outlook
While the topline contraction js now moderated as compared to 2023, I expect the company’s sales to remain under pressure due to weak demand for the company’s CPP segment product primarily in North America and the UK, which accounts for about 70% of the total segment sales. However, the company’s HPB segment is seeing better-than-expected growth in the residential door volume, driven due to growth in residential orders, which should help the company largely offset the negative impact of the weak CPP segment resulting in a flat to slightly negative revenue growth in 2024.
CPP Segment revenue distribution by geography (Company Presentation)
Although the topline is expected to almost remain flat in the near term, the company’s longer-term demand prospects look good due to global macro trends including underbuilt housing stock, rising repair and remodeling activity, growing popularity of outdoor living, and rising demand in commercial construction. The repair and remodeling activity remains resilient with aging housing inventory across the region, which should fuel the company’s sales in the coming years as a significant part of the company’s business consists of Repair and remodeling. Along with an aging inventory, the U.S. housing is underbuilt, creating a need for more homes in the future which should further drive the demand for the company’s product in the coming years.
Long Term Demand Drivers (Company Presentation)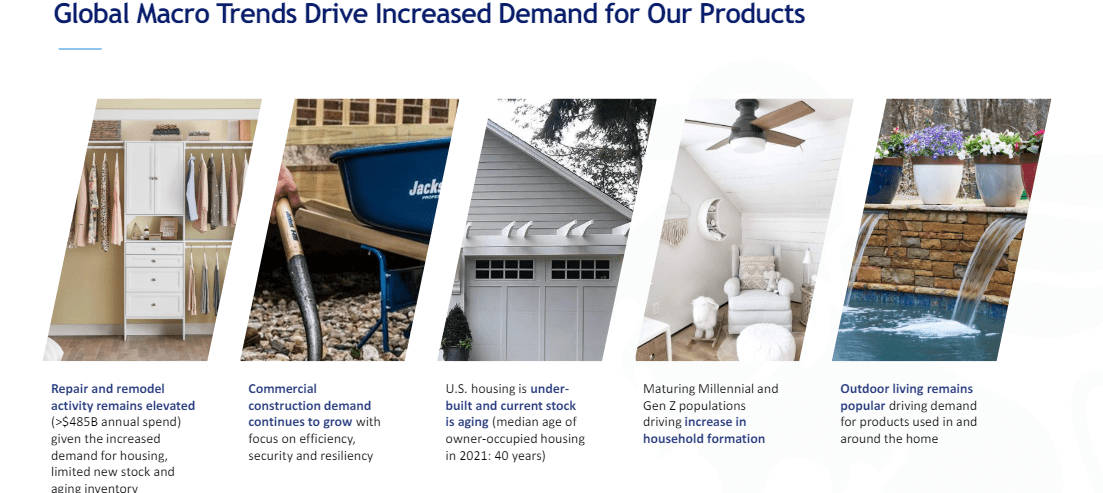
In addition to this, the company continues to invest in product innovation and technology. Also, the company also looks for potential bolt-on M&As to grow further in the longer term. The company is generating a good amount of free cash flow that is used for debt repayments, which has resulted in a net debt to EBITDA ratio of 2.8 times which is well within the target range of the company, which should further support the company in its future investments in products, tech and strategic M&As in the coming years.
As we discussed above in the last quarter’s performance, while the company sales were down during the quarter, the margins were steady and strong continuing the expansion. I expect this to continue further primarily due to the anticipated benefit from ceased operations across all four US manufacturing facilities and wood mills under its Global Sourcing Strategy to improve margins primarily in the CPP segment. Following the implementation of this, the company has experienced an improvement in manufacturing costs and decreased discretionary spending. In my opinion, as the company continues to focus on implementing this initiative of global sourcing, this should help the company to reduce costs further, improve quality, enhance innovation, and gain a competitive advantage in the marketplace further benefiting the company’s margins in the longer term.
Overall, I am expecting the topline to continue to struggle in the near term despite growth in residential orders due to weak demand for the company’s product in certain regions. However, the company is well-positioned to capitalize on long-term growth trends in repair and remodeling, commercial construction, and housing demographics.
Valuation
In the past year, the GFF stock has more than doubled reaching its all-time high of $77.99 in April as the company’s margin has expanded notably in recent quarters resulting in bottom-line growth. Currently, the company’s stock is trading at a forward P/E ratio of 13.62, based on the FY24 EPS estimate of $4.94. While the stock appears to be fairly valued to its five year average forward P/E of 12.85, on comparison with its sector median P/E, the company’s stock is still at a significant discount of approximately 30%.
GFF Valuation Grade (Seeking Alpha)
The company has experienced significant margin growth in recent quarters, and I expect this to continue further as the company continues to focus on implementing its global outsourcing initiative as its key element to improve margins further by reducing costs across North America primarily in the CPP segment in the coming quarters. While the sales looks weaker in the near term, demographic trends, as well as continued investment in product innovation and technology, should drive volume in the longer term further supporting the company’s margin resulting in bottom line growth and further improvement in the company’s valuation. Overall, in my opinion, the company’s stock is reasonably valued as compared to its closest peers which are trading at a significantly higher multiple, making the GFF stock a decent investment at the current price.
Risk
The company’s profitability has improved notably in recent quarters. The margin growth in the HPB segment was the primary driver of the overall margin expansion in the past years. The CPP segment’s profitability is also seeing improvement with reduced production costs across North America.
My thesis is built upon the expectation that the strength in the HPB segment will support the company’s overall margin growth in the coming quarters. The margin prospects of the CPP segment also look good, however, if the company’s topline continues to be under pressure, the company’s profitability could potentially be impacted badly, which might result in poor stock performance in the future.
Conclusion
As we discussed above, the company stock is trading slightly above its historical average at the moment, however, is still at an attractive discount to its sector median. I expect the topline to remain flat or decline in the low single digits in 2024, however, long-term demand prospects look promising due to demographic trends which are anticipated to drive demand for the company’s products in the coming years. The company has experienced good margin growth in the past that has helped in bottom-line expansion, and I expect this to continue further resulting in an even better valuation. Hence, considering these factors, I would recommend to “BUY” this stock.
Read the full article here