Earnings of Tompkins Financial Corporation (NYSE:TMP) will likely benefit from the falling interest-rate environment and strong regional labor markets. I’m expecting the company to report earnings of $4.41 per share for this year. Compared to my last report on the company, I have reduced my earnings estimate for the year because earnings missed my forecast for the first quarter of the year. The year-end target price suggests a mid-single-digit upside from the current market price. Further, the company is offering an attractive dividend yield. Based on the total expected return, I’m upgrading Tompkins Financial Corporation to a Buy rating.
Unemployment Rate, Commodity Prices Give Hope of Loan Growth Recovery
Tompkins Financial Corporation’s loan growth slowed down to 0.6% in the first quarter of 2024 after averaging 2.0% in the last three quarters of 2023. The first quarter’s performance was slightly below my expectation of 0.9% growth per quarter for this year given in my last report on the company.
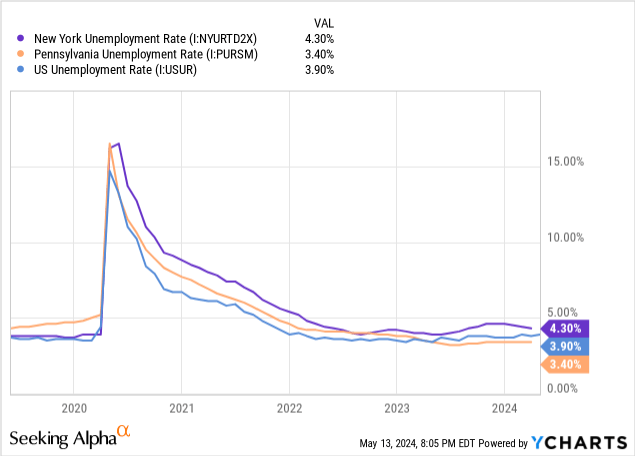
I think the first quarter’s performance is not indicative of a slowing trend as Tompkins’ markets seem to be as strong as before. The company serves the Central, Western, and Hudson Valley regions of New York and the Southeastern region of Pennsylvania. As shown below, Pennsylvania’s unemployment rate has improved in recent months and it is now doing better than the national average. New York’s unemployment rate isn’t as good; however, it too has been on a downtrend in the last few months.
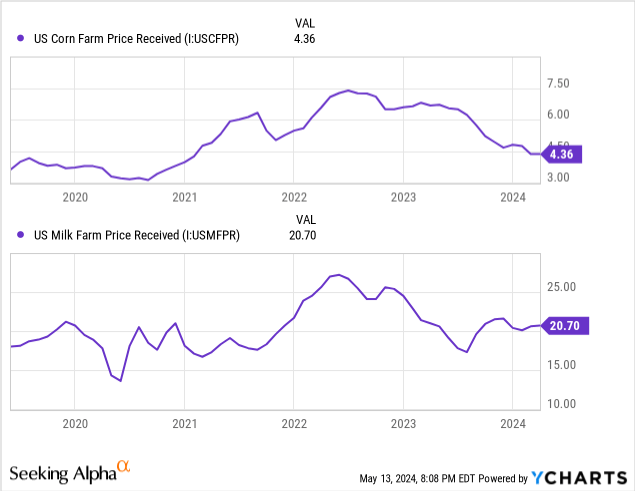
Agricultural loans make up 6% of Tompkins’ total loans; therefore, agricultural commodity prices are another indicator of credit demand. The top agricultural products in New York and Pennsylvania include milk and corn. Prices of both commodities have stabilized in recent months following disinflation.
Considering these economic factors, I believe loan growth can improve in the remainder of the year from the first quarter’s level. However, last year’s above-average performance is unlikely to be repeated. I’m expecting the loan portfolio to grow by 0.9% in each of the next three quarters, leading to full-year loan growth of 3.4%, which is close to the last five-year compounded annual growth of 3.0%. Compared to my last report on the company, I haven’t changed the growth estimate for the next three quarters, but the updated full-year growth rate is lower than before because the first quarter’s growth was slightly below my expectations.
I’m assuming other balance sheet items will grow in line with loans. The following table shows my balance sheet estimates.
| Financial Position | FY19 | FY20 | FY21 | FY22 | FY23 | FY24E |
| Net Loans | 4,878 | 5,209 | 5,033 | 5,223 | 5,554 | 5,741 |
| Growth of Net Loans | 1.8% | 6.8% | (3.4)% | 3.8% | 6.3% | 3.4% |
| Other Earning Assets | 1,301 | 1,995 | 2,369 | 1,967 | 1,742 | 1,728 |
| Deposits | 5,213 | 6,438 | 6,791 | 6,602 | 6,400 | 6,625 |
| Borrowings and Sub-Debt | 735 | 344 | 191 | 348 | 653 | 579 |
| Common equity | 662 | 716 | 728 | 616 | 669 | 818 |
| Book Value Per Share ($) | 44.2 | 48.6 | 49.7 | 42.8 | 46.7 | 57.4 |
| Tangible BVPS ($) | 37.6 | 42.0 | 43.1 | 36.1 | 40.1 | 50.8 |
| Source: SEC Filings, Author’s Estimates (In USD million unless otherwise specified) | ||||||
Fast Deposit Repricing to Boost the Margin Amid a Falling-Rate Environment
Tompkins Financial’s net interest margin dipped by nine basis points in the first quarter of 2024, after increasing by seven basis points in the last quarter of 2023. The first quarter’s performance was worse than I had previously anticipated.
Going forward, I think the margin can improve because I’m expecting the Federal Reserve to cut the Fed funds rate by 25-50 basis points in the second half of this year. Tompkins’ deposits re-price faster than assets; therefore, rate cuts should lead to immediate margin expansion this year. The gap between the assets and liabilities re-pricing within three months amounts to $1.3 billion, or 16.86% of total assets, as mentioned in the 10-Q filing and copied below.
1Q 2024 10-Q Filing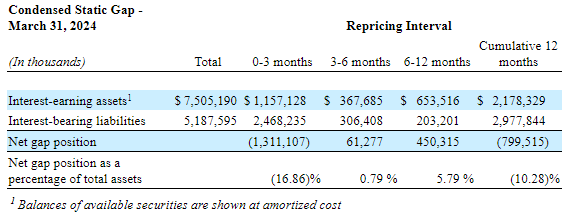
As a result, I’m expecting the net interest margin to remain unchanged in the second quarter and then grow by 10 basis points in the second half of 2024. Compared to my last report on the company, I haven’t changed my margin estimate for the last nine months of this year; however, my average margin estimate for the whole year is lower than before because the margin was lower than expected during the first quarter of the year.
Expecting Earnings of $4.41 Per Share
Apart from the expectations related to loan growth and net interest margin discussed above, I’m making the following assumptions to derive my earnings estimate for this year.
- I’m assuming the provision-expense-to-total-loan ratio will continue at the average rate for last year and the first quarter of this year.
- I’m expecting the non-interest income to normalize after the company realized high losses on the sale of securities in the third quarter of last year.
- I’m expecting the efficiency ratio (calculated as non-interest expenses divided by total revenue) to be close to the adjusted average efficiency ratio for last year and the first quarter of this year.
Considering these assumptions, I’m estimating earnings of $4.41 per share for 2024. The following table shows my income statement estimates.
| Income Statement | FY19 | FY20 | FY21 | FY22 | FY23E | FY24E |
| Net interest income | 211 | 225 | 224 | 230 | 210 | 207 |
| Provision for loan losses | 1 | 17 | (2) | 3 | 4 | 4 |
| Non-interest income | 75 | 74 | 79 | 78 | 10 | 79 |
| Non-interest expense | 182 | 184 | 190 | 196 | 203 | 201 |
| Net income – Common Sh. | 80 | 77 | 89 | 85 | 9 | 63 |
| EPS – Diluted ($) | 5.37 | 5.20 | 6.05 | 5.89 | 0.66 | 4.41 |
| Source: SEC Filings, Earnings Releases, Author’s Estimates (In USD million unless otherwise specified) | ||||||
In my last report, I estimated earnings of $4.90 per share for 2024. I’ve reduced my earnings estimate because the first quarter’s earnings missed my expectations.
Risks Appear to be Moderate
Tompkins Financial slashed its riskiness related to the securities portfolio in the third quarter of 2023 by selling a large chunk of securities that had racked up significant unrealized mark-to-market losses. The Available-for-Sale securities portfolio currently has unrealized losses of $151 million, which is around 23% of the total equity book value.
Office space loans made up just 4% of total loans at the end of March 2024, according to details given in the 10-Q filing. However, the riskiness related to this office portfolio is high because it is already seeing defaults. Nonperforming loans jumped during the fourth quarter of 2023 due to the addition of an office space and mixed-use properties relationship totaling $33.8 million.
Overall, I think Tompkins Financial Corporation’s risk level is moderate.
Tompkins Financial is Offering a High Dividend Yield of 5.2%
The dividend yield of Tompkins Financial Corporation is quite attractive at 5.2%, using the current quarterly dividend of $0.61 per share and the May 14 closing market price. The earnings estimate and current quarterly dividend suggest a payout ratio of 55%, which is higher than the 2018-2022 average payout ratio of 38% (I ignored 2023 because of the one-off securities-related loss). Nevertheless, I think the current dividend level will be maintained because a payout ratio of 55% is easily affordable.
Further, as Tompkins Financial is well capitalized, there is no threat that regulatory requirements could force a dividend cut. The ratio of total capital to risk-weighted assets was 13.43% on March 31, 2024, which is much higher than the minimum regulatory requirement of 10.0%.
Upgrading to a Buy Rating
I’m using the peer average price-to-tangible book (“P/TB”) and price-to-earnings (“P/E”) multiples to value Tompkins Financial. Peers are trading at an average P/TB ratio of 1.0 and an average fwd P/E ratio of 11.1, as shown below.
| TMP | CFFN | UVSP | OSBC | CFB | HFWA | Peer Average | |
| P/E (“ttm”) | 98.26 | NM | 9.46 | 7.42 | 9.62 | 13.96 | 10.12 |
| P/E (“fwd”) | 11.23 | 14.78 | 10.28 | 7.67 | 9.15 | 13.39 | 11.05 |
| P/B (“ttm”) | 1.01 | 0.65 | 0.79 | 1.10 | 0.91 | 0.76 | 0.84 |
| P/TB (“ttm”) | 1.18 | 0.65 | 1.00 | 1.31 | 0.95 | 1.08 | 1.00 |
| Source: Seeking Alpha | |||||||
Multiplying the average P/TB multiple with the forecast tangible book value per share of $50.8 gives a target price of $50.7 for the end of 2024. This price target implies a 7.0% upside from the May 14 closing price. The following table shows the sensitivity of the target price to the P/TB ratio.
| P/TB Multiple | 0.80x | 0.90x | 1.00x | 1.10x | 1.20x |
| TBVPS – Dec 2024 ($) | 50.8 | 50.8 | 50.8 | 50.8 | 50.8 |
| Target Price ($) | 40.5 | 45.6 | 50.7 | 55.8 | 60.8 |
| Market Price ($) | 47.4 | 47.4 | 47.4 | 47.4 | 47.4 |
| Upside/(Downside) | (14.4)% | (3.7)% | 7.0% | 17.7% | 28.4% |
| Source: Author’s Estimates |
Multiplying the average P/E multiple with the forecast earnings per share of $4.41 gives a target price of $48.8 for the end of 2024. This price target implies a 3.0% upside from the May 14 closing price. The following table shows the sensitivity of the target price to the P/E ratio.
| P/E Multiple | 9.1x | 10.1x | 11.1x | 12.1x | 13.1x |
| EPS 2024 ($) | 4.41 | 4.41 | 4.41 | 4.41 | 4.41 |
| Target Price ($) | 40.0 | 44.4 | 48.8 | 53.2 | 57.6 |
| Market Price ($) | 47.4 | 47.4 | 47.4 | 47.4 | 47.4 |
| Upside/(Downside) | (15.6)% | (6.3)% | 3.0% | 12.3% | 21.7% |
| Source: Author’s Estimates |
Equally weighting the target prices from the two valuation methods gives a combined target price of $49.7, which implies a 5.0% upside from the current market price. Adding the forward dividend yield gives a total expected return of 10.2%.
In my last report, I determined a December 2024 target price of $48.2. I adopted a hold rating at that time because the market price was higher than the target price. Since the issuance of that report, the market price has plunged. Further, my updated target price is higher than the previous target price because the peers are now trading at a higher multiple. Based on the updated total expected return, I’m upgrading Tompkins Financial Corporation to a buy rating.
Read the full article here